Home > Apt Finance >
Self-managed super fund loans
Apt Wealth Finance, powered by Acceptance Finance
Specialist lending advice for buying commercial property in your SMSF
The SMSF lending space changes constantly and rewards specialist advice. Following recent changes, SMSF loans are now available for commercial property only. We work closely with you, and alongside your financial planner, accountant and solicitor, to select suitable and competitive SMSF loans and keep the transaction smooth.
What an SMSF loan lets you do
An SMSF property loan lets your self-managed super fund borrow to buy a commercial investment property, giving your fund direct exposure to real property. Superannuation law permits this under specific rules. SMSF lending is now available for commercial property only, so residential investment purchases are no longer supported.
Lender policies vary considerably on loan-to-value ratios, trustee requirements, acceptable securities and even postcodes, so it’s important to talk to us before you buy. Funds can’t be used for residential property, vacant land or construction, and all transactions must be at arm’s length and at market rates.
How an SMSF loan comes together
From first conversation to long after settlement, here is how your broker works with you.
1
Enquire and compare
We take your enquiry and obtain quotes to compare SMSF loans, then recommend lenders for you to choose from.
2
Set up the structure
With your advisers, you establish the required trust structures, including a separate bare or property trust that becomes the legal owner of the property.
3
Apply with advice
You supply the documents, including trust deeds and advice certificates from your planner, accountant or solicitor, and we submit the application.
4
Approve and settle
The lender reviews and approves, documents are prepared and signed, and the loan settles. Set-up usually takes six to eight weeks.
Key things to know about SMSF lending
SMSF finance is specialised. These are the points that matter most:
Who’s eligible
Australian residents with an existing SMSF, or one being established, including funds refinancing an existing SMSF commercial investment property loan.
What you can buy
A single commercial investment property, including business premises leased to your own business at market rent (business real property). Not residential property, vacant land or construction, and always at arm’s length and market rates.
The trust structure
A separate bare or property trust holds legal title while your SMSF is the beneficial owner and receives the rent, which can go towards repayments.
Advice required
Most lenders require you to obtain your own financial and legal advice, and some won’t approve until the trust deeds have been vetted by panel solicitors.
Women, retirement and long-term security
A practical guide to building the retirement you want, written for the way women actually move through their working lives and beyond.
- How to understand and strengthen your super position at any age
- Catch-up strategies after career breaks or part-time work
- Smart, tax-effective ways to draw income in retirement
- Planning for aged care, including keeping the family home
- The most common retirement mistakes, and how to avoid them
Apt Wealth Partners · Whitepaper
Women, retirement and long-term security
Meet the brokers behind your loan
Our finance specialists bring a large panel of lenders, deep knowledge of lender policy and a best interests duty to every conversation. Whatever you’re financing, you’ll find someone ready to listen first and help you plan with confidence
Aimee Telford

Aimee Telford
Personal Mortgage Adviser
Aimee Telford is a Personal Mortgage Adviser at Apt Wealth Partners, with a diverse background in the building and novated lease industry.
Melbourne
Albert Kavcic
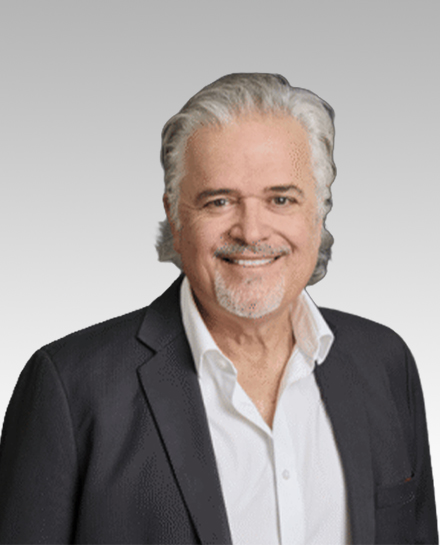
Albert Kavcic
Finance Broker
Albert Kavcic is a Finance Broker at Acceptance Finance, working with families across Keilor and the surrounding Melbourne suburbs to secure home loans and grow investment portfolios.
Keilor/Keilor East, Melbourne
John Empey
John Empey
Finance Broker
John Empey is a Finance Broker at Acceptance Finance, working from his own office in Warrawee to help clients across Sydney's Upper North Shore with home loans, investment loans and refinancing.
Warrawee, Sydney
Matt Mannaert
Matt Mannaert
Finance Broker
Matt Mannaert is a Finance Broker at Acceptance Finance and one of the country's top-performing mortgage brokers, known for his work with property investors.
Balwyn, Melbourne
Matthew Papuga
Matthew Papuga
Finance Broker
Matthew Papuga is a Finance Broker at Acceptance Finance, splitting his time between the Balwyn office and Hoppers Crossing to stay available to clients across both areas.
Balwyn and Hoppers Crossing, Melbourne
Minji Kim
Minji Kim
Finance Broker
Minji Kim is a Finance Broker at Acceptance Finance, an award-winning broker known across Balwyn and Ringwood, and a trusted contact for Melbourne's Korean community.
Balwyn and Ringwood, Melbourne
Richie Kasai
Richie Kasai
Finance Broker
Richie Kasai is a Finance Broker at Acceptance Finance, based out of the Balwyn office and known across Kew and Doncaster.
Balwyn, Melbourne
Russel Shaw
Russel Shaw
Finance Broker – Northern Rivers
Russel Shaw is a Director of Acceptance Finance and its Senior Finance Broker for the Ocean Shores office, working across the Northern Rivers region and South East Queensland, with the backing of the Melbourne head office.
Ocean Shores, Northern Rivers NSW
Sally Whitworth
Sally Whitworth
Finance Broker
Sally Whitworth is a Finance Broker at Acceptance Finance, focused on educating clients so they can make informed decisions about their loan choices.
Balwyn, Melbourne
Sharon D'Costa
Sharon D'Costa
Finance Broker
Sharon D'Costa is a Finance Broker at Acceptance Finance, helping clients across home loans, refinancing, SMSF lending, reverse mortgages and commercial finance.
Melbourne
What our clients often ask us
Can my SMSF buy residential property?
No. Following recent changes, SMSF lending is now available for commercial investment property only, so residential investment purchases are no longer supported. If you already hold a residential property in your SMSF, talk to us and your advisers about your options.
What can my SMSF buy with an SMSF loan?
A single commercial investment property, including business premises leased to your own business at market rent. You can’t use the funds for residential property, vacant land or construction, and all transactions must be at arm’s length and conducted at market rates.
What is a limited recourse loan?
It means that if the loan defaults, the lender’s recourse is limited to the property held in the separate trust, not the other assets in your SMSF. It’s a key protection built into SMSF borrowing.
How long does it take and what advice do I need?
Set-up usually takes six to eight weeks. Most lenders require you to obtain your own financial and legal advice, and some need the SMSF and bare trust deeds vetted by panel solicitors before approval.
Reading for your finance journey
Practical guidance on borrowing, structuring finance and the decisions ahead of you.
What you can (and can’t) invest in through an SMSF
David Maddock
Mar 13, 2026
Self-managed super funds (SMSFs) often attract attention because they offer something many investors value: control. Instead of relying on a large super fund to make investment decisions on your behalf,...
Read more
Tax-effective strategies to manage superannuation in FY 2025/26
Connie Yi
Jul 04, 2025
As we enter the 2025/26 financial year, superannuation remains one of the most powerful and tax-effective ways to build long-term wealth in Australia. The start of a new tax year...
Read more

Using an SMSF to purchase commercial premises for medical practitioners
David Maddock
Jan 16, 2024
As a medical practitioner and business owner, one of the key components of your financial journey is deciding whether to acquire or invest in commercial premises for your practice. In...
Read more
Explore more on the Apt Wealth Partners blog.
Get SMSF lending right from the start
Book a no-obligation chat and we’ll work with you and your advisers to structure your SMSF loan properly.
Prefer to talk now? Call us on 1800 801 277
Contact Us
Leave your details below, and an experienced adviser will be in touch.
"*" indicates required fields